the No1 Google Ranking Luxury Property Magazine
What The Latest ONS Housing Data Reveals About The UK Luxury Market
05.10.26Official government housing statistics often reflect broader mass-market movements, yet beneath the headline indices lies clear evidence of the forces reshaping prime and super-prime real estate.
The latest statistical release from the Office for National Statistics (ONS)—the Private Rent and House Prices, UK: September 2026 bulletin—illustrates an accelerating structural divide between transactional values and lettings cash flow. While regional markets across the North and Midlands posted steady capital growth, London recorded the lowest annual percentage change in the country, with average sale prices dropping 3.3% in the 12 months to July 2026 to £569,000—now £19,000 below its recent peak.
In contrast, the rental market tells the opposite story. The Price Index of Private Rents (PIPR) shows private rent inflation across the UK ticking upward to 3.8% in the year to August 2026, driven by an acute imbalance in England’s prime metropolitan centres.
For high-net-worth investors and family offices tracking UK residential assets, the ONS metrics provide essential clarity on where capital preservation and yield generation are diverging.
London’s capital repricing: The buyer’s window
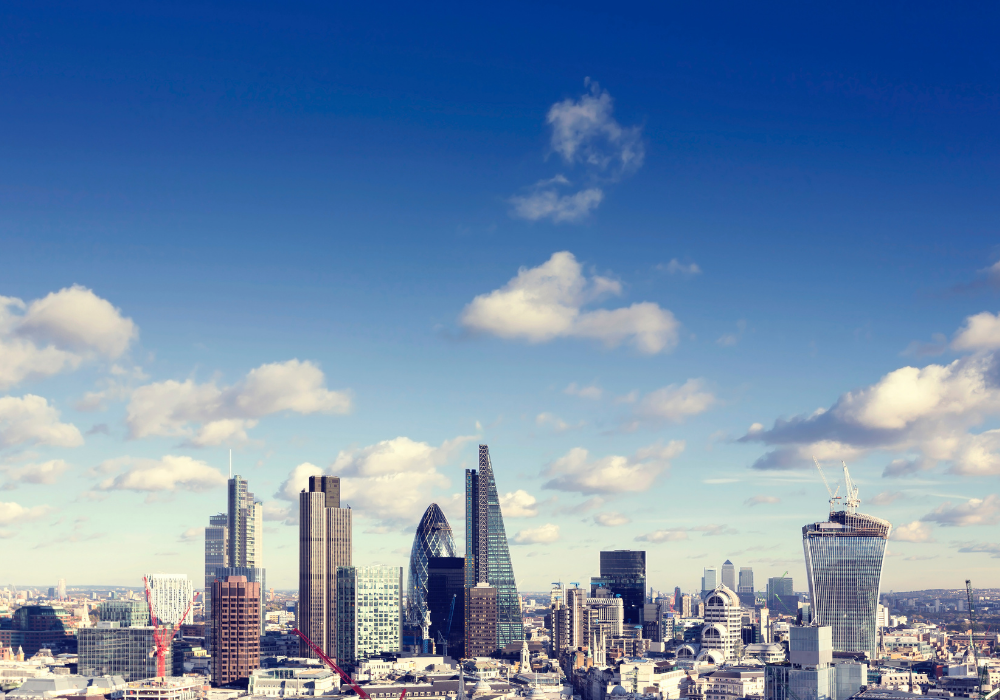
While headline UK house prices grew modestly—climbing 1.1% in England and up to 4.9% in regional hotspots like the North East—the capital continues its disciplined recalibration.
The 3.3% annual contraction in London values reflects persistent headwinds in the mortgaged domestic mid-tier, combined with buyer caution surrounding non-dom tax adjustments and the scheduled 2028 High Value Council Tax Surcharge. Inner London boroughs, historically the bellwethers of prime performance, have shouldered the brunt of this softening.
For prime central buyers transacting in foreign currencies or balance-sheet cash, however, this adjustment has opened an advantageous negotiating window. With nominal values lagging regional peers and trading well below previous historical peaks, international purchasers are actively exploiting vendor pragmatism to secure generational assets at favourable per-square-foot entry points.
UK rentals in Kensington & Chelsea
While capital values face gentle downward pressure, prime lettings have reached historic territory. According to the ONS bulletin, London maintains the highest average monthly rent of any UK region at £2,332, but granular local authority data highlights the extreme concentration of wealth at the very top.
The Royal Borough of Kensington and Chelsea registered the highest average monthly rent in the entire United Kingdom at £3,690 in August 2026. This stands in stark contrast to the UK's least expensive rental district (Dumfries and Galloway at £558), making Kensington and Chelsea more than six times more expensive than the national floor. Outside the capital, only elite university and executive commuter hubs like Oxford (£1,963) approach London's baseline.
This rental surge underscores the structural shift currently defining prime London: internationally mobile professionals, corporate leaders, and high-net-worth families are choosing long-term, multi-year tenancies over immediate property purchases. This flight to flexibility has placed an immense premium on turnkey, professionally managed townhouses and lateral apartments, eliminating void periods for prime landlords.
The 4-bed premium
The ONS breakdown by property size reveals where tenant demand is driving the steepest escalation. Across the UK, rents for detached properties averaged £1,589 in August 2026, while properties with four or more bedrooms commanded £2,080 per month—the highest of any category, compared to £1,136 for single-bedroom homes.
In prime central postcodes, this multi-bedroom premium is amplified. Family-sized townhouses across Kensington, Chelsea, Belgravia, and St John's Wood face a structural deficit of available listings. As institutional developers focus primarily on high-density luxury apartment schemes, standalone family residences with private gardens and secure garaging have become the tightest asset class in the rental ecosystem, insulating landlord cash flows from broader macroeconomic cycles.
Implications for prime portfolios, Abode2 concludes
The September 2026 ONS data points to three clear conclusions for luxury property stakeholders:
First, the buy-to-let equation at the upper end of the market has shifted from short-term capital appreciation to long-term income security. Prime London yields have strengthened as rents have climbed while capital values underwent price discovery.
Second, the disparity between England's regional capital performance and London’s value softening confirms that the capital is behaving as an independent international market. Disconnected from mainstream domestic mortgage cycles, Prime Central London is resetting to reflect direct cash liquidity and tax policy changes.
Finally, for overseas capital deploying into the UK, current market dynamics represent a classic entry posture: rental yields are historically elevated, inventory at the upper end remains tightly held, and disciplined buyers retain maximum pricing power across prime negotiating tables.
Receive a print copy of Abode2, or subscribe to our digital or print editions here.

Categories
Property Of The Week
-
 Property Of The Week: Modern Architectural Drama In The Heart Of Marylebone
28.09.26
- Property Of The Week: Contemporary Grandeur At Villa Musa, Lake Como 21.09.26
- Property Of The Week: Duplex Penthouse With Panoramic Sea Views, Roca Llisa, Ibiza 11.09.26


Abode Affiliates



COPYRIGHT © Abode2 2012-2026