the No1 Google Ranking Luxury Property Magazine
What Is A Branded Residence? Abode2 Explores The Real Estate Phenomenon
12.10.26Once regarded as a niche novelty confined to flagship hotel towers in New York or London, the branded residence has matured into one of the most resilient, high-conviction asset classes in global prime real estate.
Over the past decade, the sector has expanded by more than 160%, establishing itself as a core wealth depository for international high-net-worth individuals and family offices.
Yet as the market broadens from classic hospitality partnerships to encompass automotive icons, haute horlogerie, and heritage fashion houses, buyers and investors increasingly ask: what fundamentally defines a branded residence, why does the sector consistently command double-digit valuation premiums, and where is the next frontier of growth?
Abode2 examines the architecture, operational mechanics, and global market dynamics driving this multi-billion-dollar evolution.
The mechanics of branded living
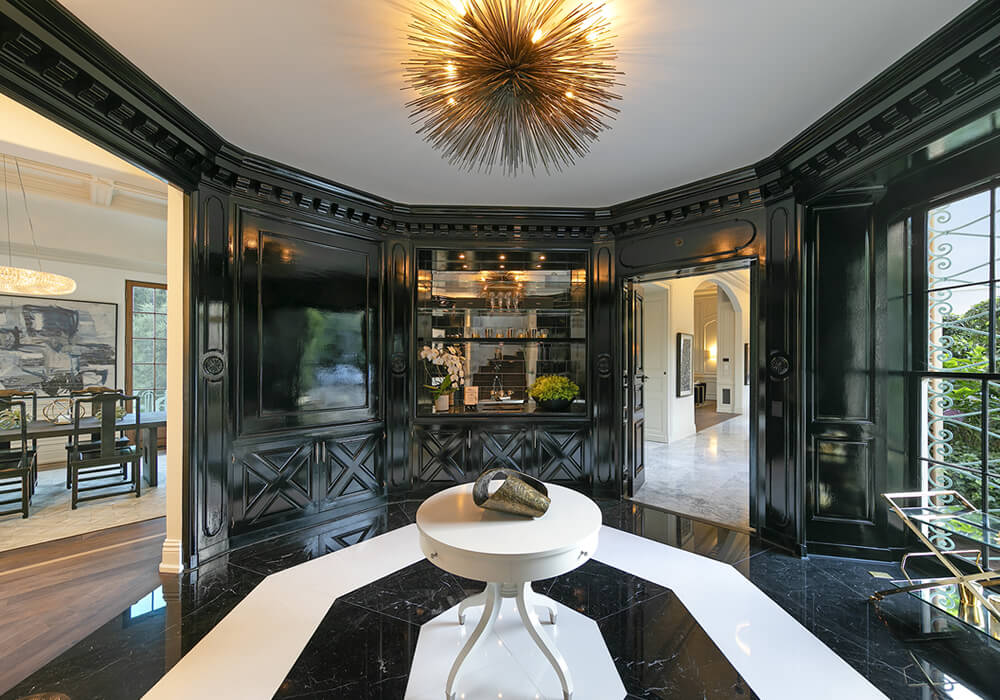
At its core, a branded residence is a residential property—typically an apartment, penthouse, or standalone villa—developed, designed, and operated in formal partnership with a recognised luxury brand.
The sector divides into two primary models:
-Residential units developed within or directly adjacent to a five-star hotel property (such as Four Seasons, The Ritz-Carlton, Mandarin Oriental, or Aman). Residents benefit from the hotel's infrastructure, including 24-hour concierge, in-residence dining, housekeeping, private spa access, and priority booking across the operator’s global portfolio.
- High-density towers or horizontal private estates that carry the intellectual property, design DNA, and curated lifestyle standards of a non-hospitality luxury brand. This segment has accelerated rapidly through partnerships with automotive marques (Bugatti, Porsche, Bentley, Aston Martin) and fashion houses (Armani/Casa, Fendi Casa, Bvlgari).
Regardless of the model, a genuine branded residence is distinguished by professional operational stewardship. The brand does not simply license its name to a developer's facade; it enforces rigorous construction standards, oversees spatial layouts, and manages long-term facility operations, ensuring the building’s service delivery and maintenance remain consistent across decades.
Price premiums and de-risked capital
The sustained commercial appetite for branded residences is underpinned by clear valuation metrics. Global property data reveals that branded schemes achieve an average international price premium of 25% to 35% over comparable unbranded luxury homes in the same submarket. In emerging or high-growth resort enclaves, this uplift can surpass 40%.
For developers, aligning with an internationally recognised marque compresses sales absorption timelines and significantly de-risks financing, allowing schemes to secure off-plan deposits far faster than unbranded alternatives.
For high-net-worth buyers, the premium represents an investment in:
- In secondary resale markets, branded units trade with higher international visibility and liquidity, as foreign buyers rely on brand prestige as a proxy for build quality and legal security.
- Complete on-site management, security, and maintenance eliminate the administrative burden of owning multi-jurisdictional private homes.
When placed into fully managed rental pools, branded residences command superior average daily rates (ADRs) and higher occupancy levels, supported by the parent brand’s global reservation networks and loyal clientele.
Global hotspots for branded residences
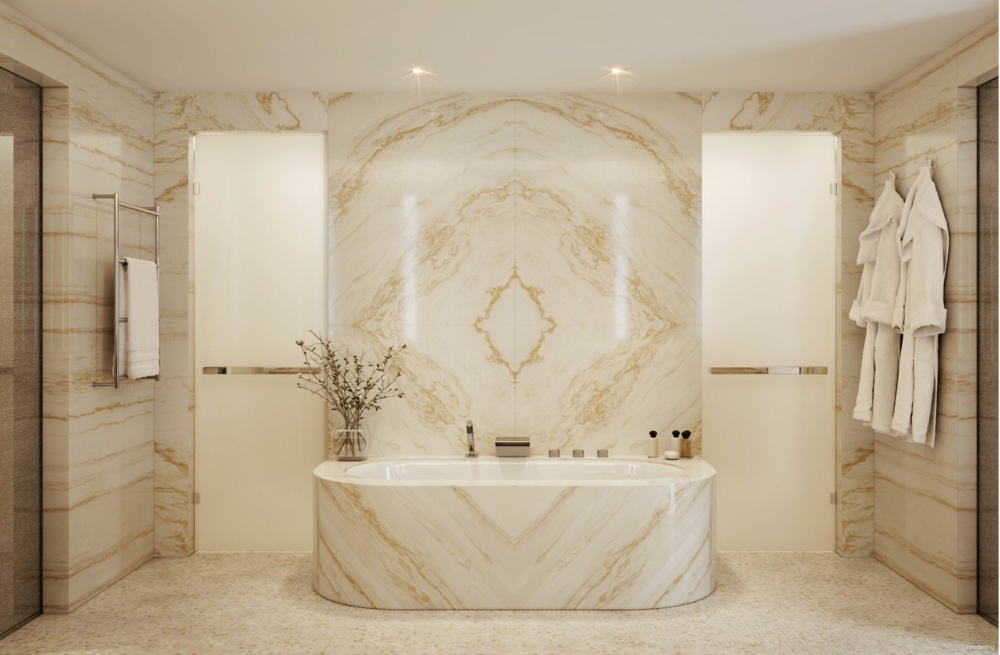
Historically, the United States dominated the sector, anchored by urban strongholds in New York and Miami alongside mature resort corridors in Aspen and Hawaii.
However, over the past five years, the global centre of gravity has shifted dramatically toward the Middle East. Dubai has established itself as the world’s most concentrated branded residential hub, registering dozens of landmark schemes across Palm Jumeirah, Business Bay, and Downtown Dubai.
Now, institutional focus is pivoting toward underserved prime markets where private wealth is deep, but branded residential supply has historically been scarce.
A spotlight on Australia
A prime example of this geographic expansion is Australia. According to market research by JLL, the Australian luxury sector stands at the threshold of a defining era. Despite Sydney ranking sixth globally for private wealth property acquisitions, the nation has historically suffered from a severe structural undersupply of branded schemes.
Unlike Asian and Middle Eastern markets—which were largely seeded by cross-border speculative investment—Australia’s demand is being propelled by domestic wealth. Decades of sustained residential capital growth have created an equity-rich cohort of downsizers aged 55 to 75. These buyers are selling large multi-million-dollar suburban estates in Sydney and Melbourne to acquire turnkey, fully serviced apartments in the city or along the coast, willing to absorb premium strata and service charges in exchange for five-star hotel-level care.
Development momentum is already materialising across key Australian corridors:
- Sydney and Melbourne: Urban towers pairing bespoke architecture with ultra-luxury hotel operators and fashion houses.
- The Gold Coast and Brisbane: Beachfront towers in Broadbeach and Surfers Paradise, alongside Olympic-driven urban regeneration in Brisbane, where branded living meets an active leisure lifestyle.
The future for branded real estate
The branded residence has evolved beyond a marketing label to become a distinct asset class within prime real estate portfolios. As global high-net-worth wealth expands and the demand for seamless, serviced urban living intensifies, the sector is moving toward greater specialisation—embracing biological wellness integrations, sustainable ESG engineering, and bespoke private member amenities.
For developers, brands, and private collectors alike, the model provides an enduring truth: in an increasingly crowded global market, world-class design combined with institutional hospitality standards continues to command the ultimate capital premium.

Categories
Property Of The Week
-
 Property Of The Week: A Botanical Grandeur At Acacia, Al Barari
12.10.26
- Property Of The Week: The Crown Duplex Penthouse At 100 George Street W1 07.10.26
- Property Of The Week: Modern Architectural Drama In The Heart Of Marylebone 28.09.26


Abode Affiliates



COPYRIGHT © Abode2 2012-2026